


Geschäftsführender Partner, vereidigter Buchprüfer, Steuerberater, Rechtsanwalt
Audiences
Contact
General enquiries
Firm
Contact
General enquiries
 KI Bild
Service
A handover has three sides: the company, the family and the tax office. We align them with one another while all three still have room for manoeuvre.
Company succession should be well prepared and structured. If you start in good time, you have corresponding scope for structuring: tax relief rules need lead time, successors need to be trained, and a company that does not function without its owner is difficult to transfer.
If you start late, you have fewer options. It is then often no longer a question of optimisation, but above all of limiting the tax burden and holding the business together.
We support the handover from the valuation through the contractual structuring to the tax implementation. To do so, specialists in law, tax and valuation work together at our firm in a dedicated expert team.
Contacts
Geschäftsführender Partner, vereidigter Buchprüfer, Steuerberater, Rechtsanwalt
Partner, Diplom-Kaufmann, Wirtschaftsprüfer und Steuerberater
Partner, Steuerberater, Fachberater für Unternehmensnachfolge (DStV e.V.)
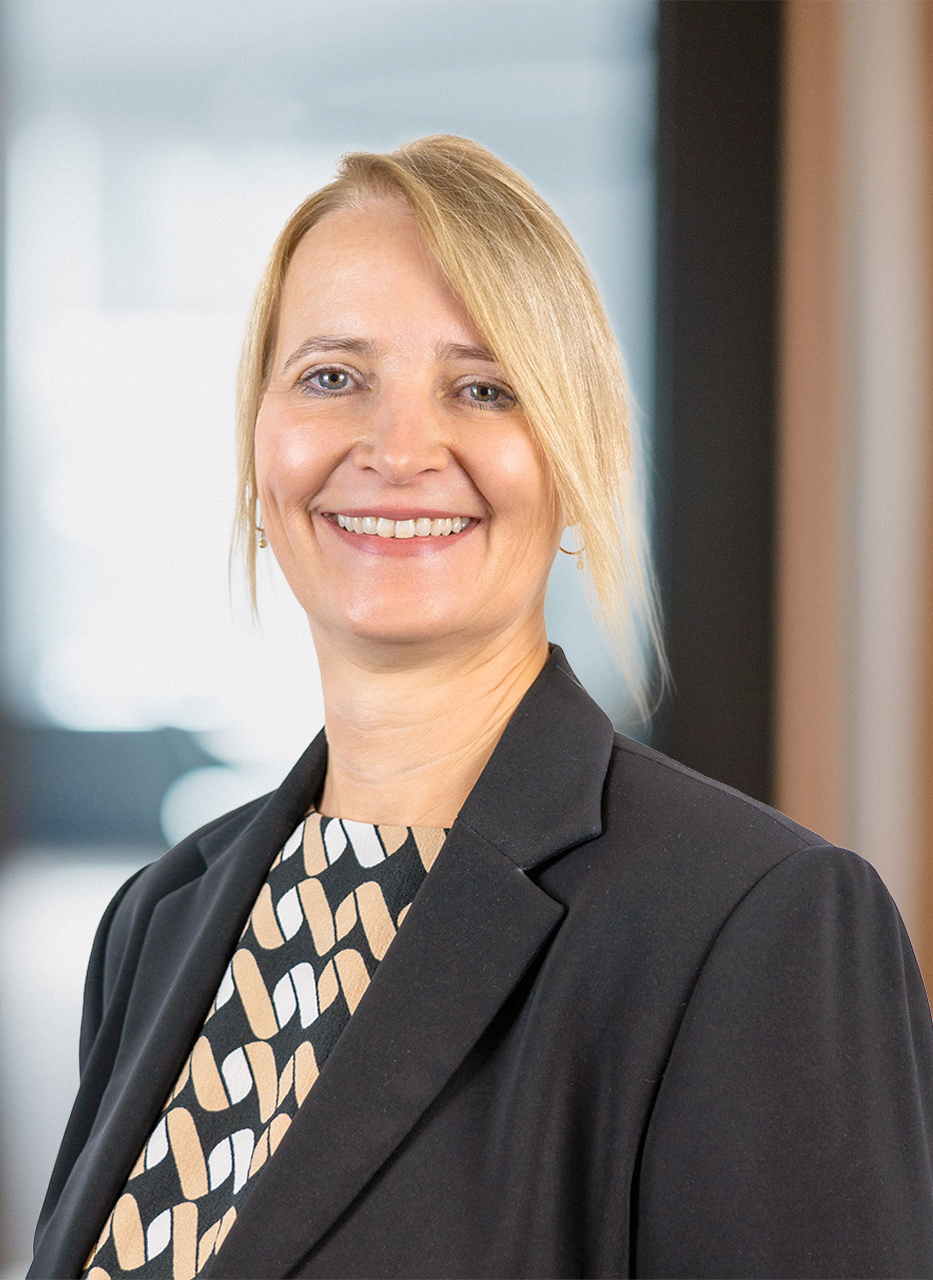
Partnerin, Rechtsanwältin
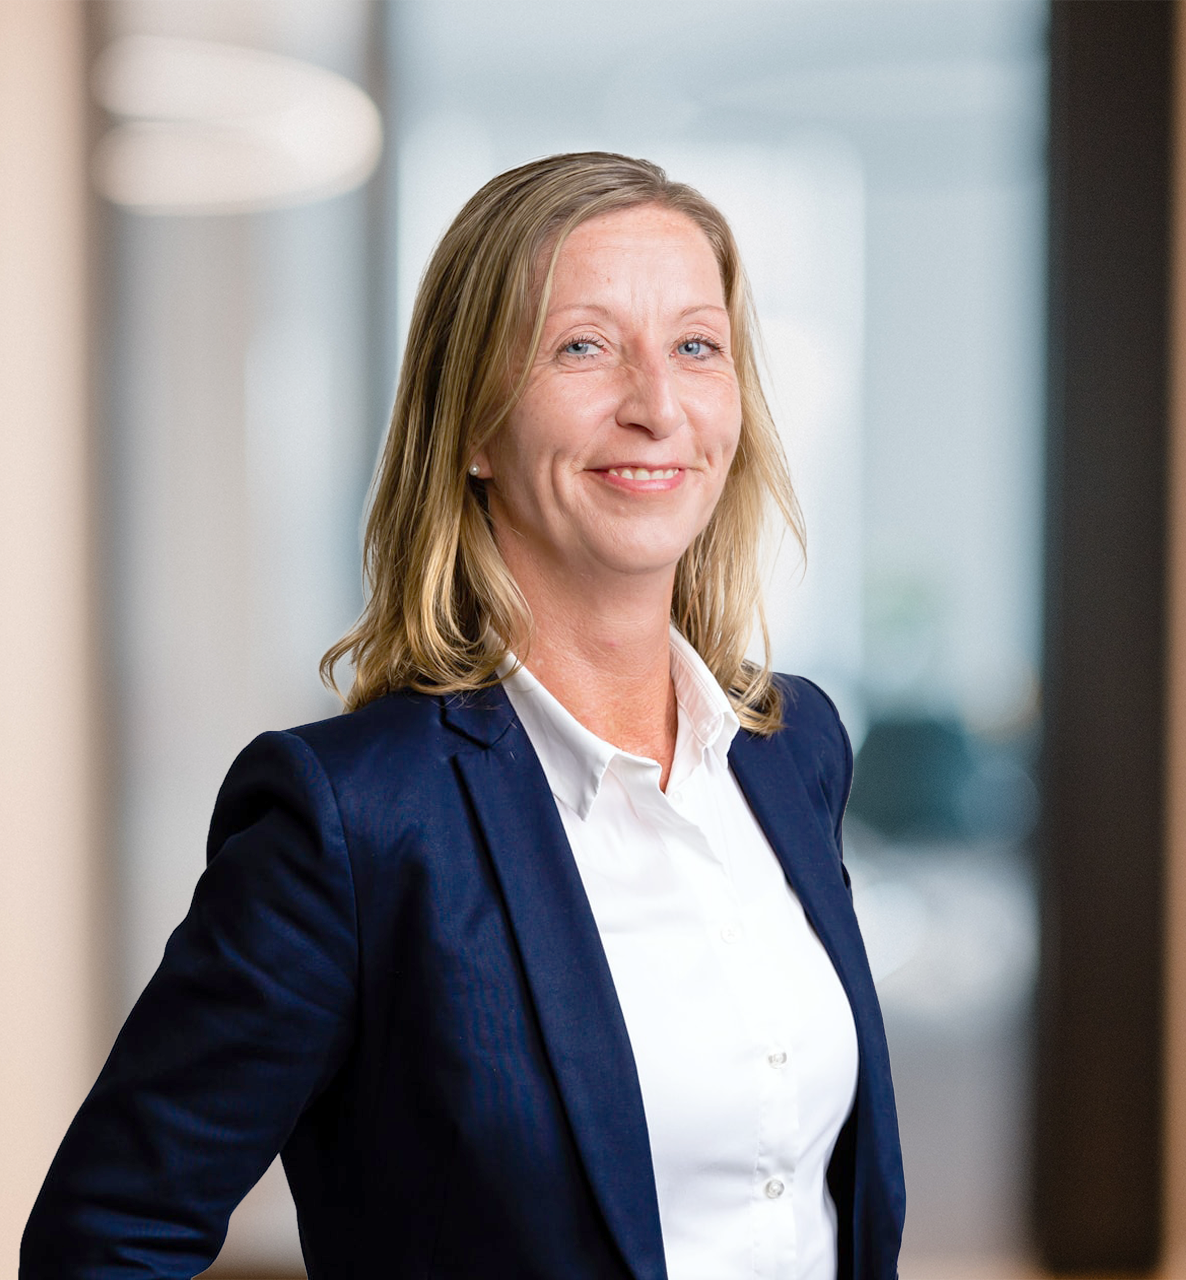
Partnerin, Steuerberaterin
Answers to the questions our clients ask us most often about succession.
Five to ten years before the planned handover date. Tax structuring only takes effect after certain periods have passed, and successors need time to grow into their role.
That depends on the legal form, the asset structure and whether the relief rules apply. The range extends from a largely tax-free transfer to a considerable tax burden.
In that case, the alternatives are often a sale, a management buy-out or a foundation solution. Each solution has its own tax and legal consequences. Together with you, we work out which individual solution is right for you and your purposes.
For inheritance and gift tax purposes, the valuation is generally carried out under the German Valuation Act (Bewertungsgesetz). In addition, a valuation in accordance with IDW S 1 can be useful, for example to demonstrate a lower company value.
In most cases, yes. If the will and the articles of association contradict each other, the provisions of the articles of association take precedence. This often leads to a result that was not intended. More on this on our Inheritance law page.
Are you thinking about a handover or would you like an existing plan reviewed? Talk to us.

Contact
Are you thinking about a handover or would you like an existing plan reviewed? Talk to us.
